
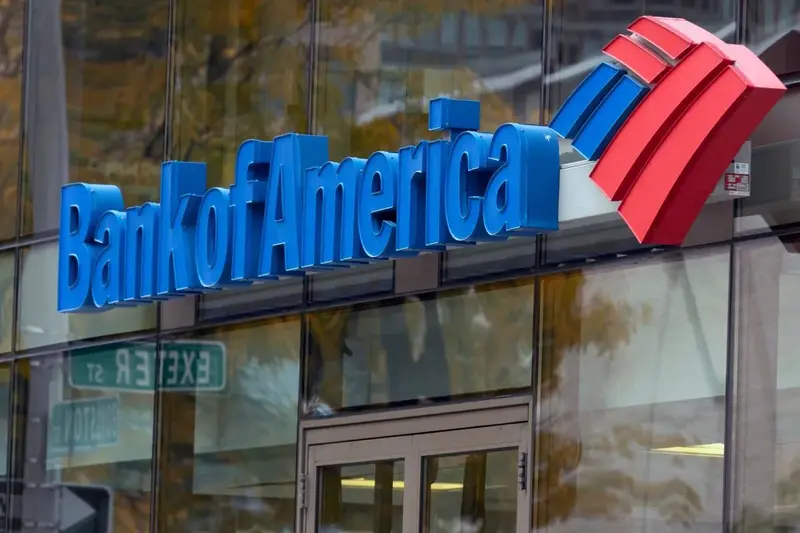
Bank of America’s latest money laundering penalties have renewed scrutiny of financial crime compliance across traditional banking and cryptocurrency markets.
The enforcement action highlights how major financial institutions struggle to detect suspicious transactions and meet regulatory obligations.
It also draws fresh comparisons with previous penalties against cryptocurrency exchange Binance and Canadian lender TD Bank. The cases raise questions about regulatory oversight and accountability across both traditional finance and digital assets.
Bank of America faces $1.21 billion in money laundering penalties
The U.S. Treasury Department imposed more than $1.21 billion in penalties on Bank of America for anti-money laundering and sanctions violations.
According to the Financial Crimes Enforcement Network (FinCEN), the bank failed to address significant national security risks. These included Chinese money laundering networks and suspicious financial activity along the U.S. southwest border.
The settlement ranks as the Treasury Department’s third-largest enforcement penalty.
The Office of the Comptroller of the Currency (OCC) imposed a record $750 million fine on Bank of America. Meanwhile, the Office of Foreign Assets Control (OFAC) secured an additional $11.6 million settlement.
OFAC linked its findings to apparent sanctions violations involving Iran, Russia, narcotics trafficking, and international terrorism.
Treasury Secretary Scott Bessent said the enforcement action demonstrated that major banks must also comply with financial crime laws.
OCC exposes major failures in Bank of America’s transaction monitoring
The OCC found that Bank of America’s inadequate monitoring systems allowed trillions of dollars in transactions to escape proper scrutiny.
According to regulators, those failures delayed suspicious activity reports covering billions of dollars in potentially illicit transactions.
The agency also alleged that Bank of America knew about unresolved compliance weaknesses for years but failed to address them.
Furthermore, regulators identified shortcomings in staff qualifications, compliance leadership, and targeted anti-money laundering training.
These deficiencies contributed to inaccurate investigations and overdue regulatory reports, according to the OCC.
Under the Bank Secrecy Act of 1970, financial institutions must monitor transactions, maintain records, and report suspicious activity.
Such reports help FinCEN and law enforcement trace illicit funds, uncover criminal networks, and investigate cross-border financial crimes.
Bank of America acknowledged its compliance violations and accepted responsibility for improving its financial crime controls.
The lender said it had invested billions of dollars in technology and recruited thousands of employees to strengthen compliance.
However, the bank acknowledged that additional improvements remained necessary.
Binance’s $4 billion penalty revives crypto money laundering comparisons
Bank of America’s settlement has renewed comparisons with Binance, which faced a $4 billion penalty in 2023.
Binance admitted violating the Bank Secrecy Act and sanctions requirements after failing to implement adequate suspicious transaction monitoring.
Founder Changpeng Zhao resigned as chief executive following the settlement. Authorities also imposed a five-year compliance monitoring requirement.
A federal court later sentenced Zhao to four months in prison over his failure to maintain effective anti-money laundering controls.
Former Attorney General Merrick Garland criticized Binance for using technological innovation while disregarding established financial laws.
Meanwhile, TD Bank agreed to approximately $3 billion in penalties in 2024 after regulators uncovered widespread money laundering control failures.
Garland accused TD Bank of creating conditions that allowed criminals to exploit its financial services.
Together, the three enforcement actions highlight compliance failures across banking and cryptocurrency businesses.
The comparisons also refocus attention on whether money laundering risks stem from specific financial technologies or inadequate institutional oversight.